The Business Research Company’s Forecast Report on Electronic Chemicals and Materials Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON, UNITED KINGDOM, October 12, 2026 /EINPresswire.com/ — The electronic chemicals and materials market is becoming an increasingly vital segment within the broader chemicals industry, driven by rapid advancements in technology and semiconductor manufacturing. As demand for cutting-edge electronic devices intensifies, this sector is set to experience substantial growth and innovation in the coming years. Let’s explore the market’s size, growth factors, key players, and emerging trends shaping its future.
Projected Market Size and Expansion of the Electronic Chemicals and Materials Market
The value of the electronic chemicals and materials market is forecasted to surpass $131 billion by 2030. This market forms a significant portion of its parent specialty chemicals industry, which is anticipated to reach around $1,001 billion by the same year. Within the even larger chemicals sector, expected to hit $7,007 billion by 2030, electronic chemicals and materials will account for nearly 2% of the total market value, highlighting its meaningful contribution to the overall industry.
Request A Free Sample Of The Electronic Chemicals And Materials Market Report
https://thebusinessresearchcompany.com/sample_request?id=46394925&type=smp&name=Electronic%20Chemicals%20And%20Materials%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Strong Growth Trajectory for Electronic Chemicals and Materials Through 2030
Looking ahead, the electronic chemicals and materials market is predicted to grow at a compound annual growth rate (CAGR) of 10% until 2030. This robust pace reflects escalating demand and ongoing technological advancements, which continue to push the boundaries of what these materials can achieve within semiconductor and electronics manufacturing.
Asia-Pacific Positioned as the Leading Region in Electronic Chemicals and Materials
By 2030, the Asia-Pacific region is expected to dominate the electronic chemicals and materials market, reaching a valuation of $48 billion, up from $32 billion in 2025. This growth corresponds to a CAGR of 8%, driven by the expansion of semiconductor fabrication facilities, investments in next-generation electronics plants, increasing use of ultra-high-purity semiconductor materials, and government initiatives focused on building self-sufficient electronics supply chains.
Access The Detailed Electronic Chemicals And Materials Market Report Here
https://thebusinessresearchcompany.com/report/electronic-chemicals-and-materials-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
China’s Dominance in the Electronic Chemicals and Materials Sector
China is set to be the largest single country market within electronic chemicals and materials by 2030, commanding $24 billion compared to $16 billion in 2025, representing an 8% CAGR. This surge is fueled by an increase in consumer electronics production, growth in local wafer fabrication facilities, demand for specialty materials in sophisticated manufacturing, and ongoing governmental programs aimed at strengthening the domestic semiconductor ecosystem.
Key Segments Defining the Electronic Chemicals and Materials Market
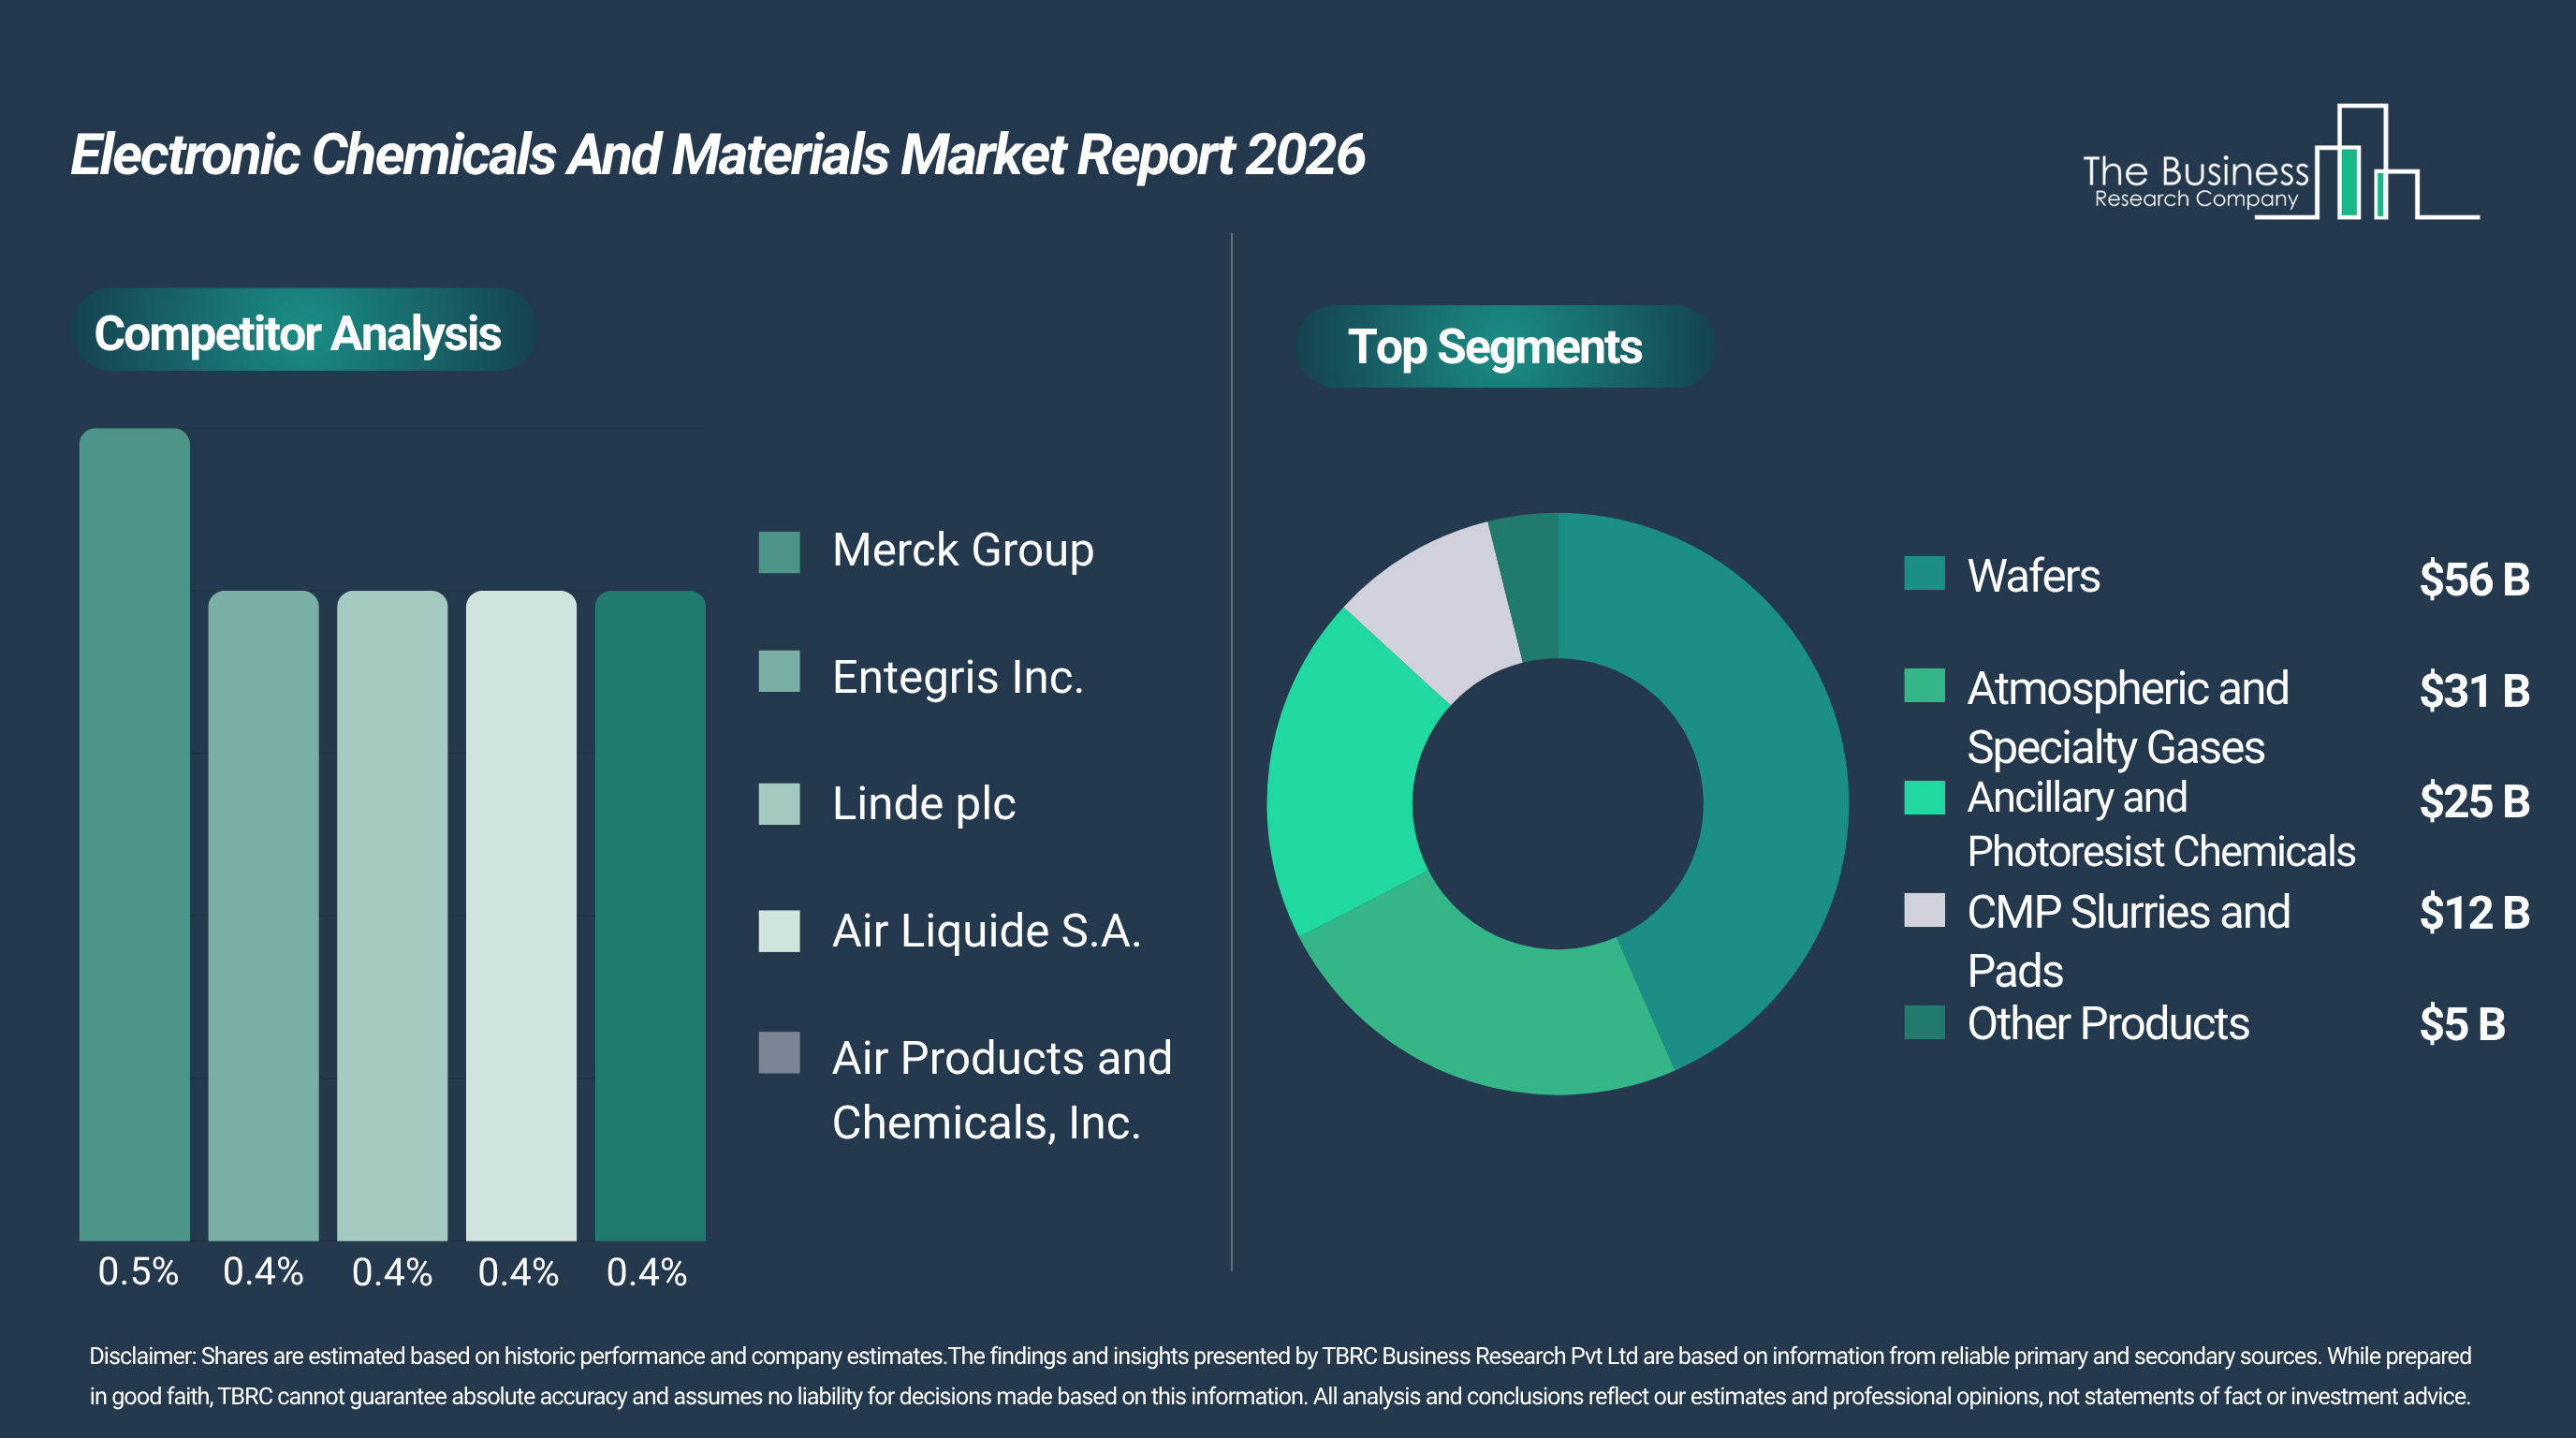
The market breaks down into several main product categories, including wafers, atmospheric and specialty gases, ancillary and photoresist chemicals, CMP (chemical mechanical planarization) slurries and pads, and other related products. Wafers stand out as the largest segment in 2030, expected to make up 43% of the market or $56 billion. This segment benefits from higher production volumes of advanced integrated circuits, adoption of larger-diameter wafers for efficiency, improved wafer processing technology, and the demand for performance-enhancing substrates.
Application and End-User Segmentation in Electronic Chemicals and Materials
From an application standpoint, the market is categorized into wafer fabrication and packaging processes. Regarding end users, the market serves semiconductor manufacturers, integrated device manufacturers, electronics and electrical component producers, and display panel manufacturers, each contributing to the demand for high-purity materials and specialized chemicals essential for manufacturing.
What’s Fueling Growth in the Electronic Chemicals and Materials Market
One major force propelling market growth is the surging global demand for semiconductors and advanced electronic gadgets. Increased production of smartphones, computers, consumer electronics, industrial automation equipment, and data center infrastructure requires more ultra-high-purity wafers, specialty gases, photoresists, CMP materials, and other key chemicals. The trend toward smaller chip nodes and complex designs further elevates material performance requirements. This dynamic is expected to add about 2.5% annual growth to the market.
Expansion of AI, 5G, IoT, and Electric Vehicles as a Growth Catalyst
The rapid adoption of artificial intelligence, 5G networks, Internet of Things (IoT) devices, and electric vehicles is boosting the production of sophisticated semiconductor chips. These advanced chips depend on specialized deposition materials, etchants, specialty gases, and cutting-edge lithography chemicals. This technological evolution is forecast to contribute roughly 2.3% yearly growth to the electronic chemicals and materials market.
Rising Investments in Semiconductor Manufacturing Infrastructure
Another significant driver is the global increase in investments toward building and expanding semiconductor manufacturing plants. Government incentives, efforts to localize supply chains, and the construction of new wafer fabs, packaging facilities, and research centers in key regions create sustained demand for ultra-high-purity chemicals and materials used throughout chip fabrication. This factor is expected to deliver an approximate 2.1% annual growth rate.
Most Promising Segments Offering Growth Potential
The segments involving wafers, atmospheric and specialty gases, ancillary and photoresist chemicals, CMP slurries and pads, along with other products, represent the top opportunities for market expansion. Collectively, these segments could add over $51 billion in value between 2025 and 2030. Wafers alone are projected to grow by $21 billion, atmospheric and specialty gases by $13 billion, ancillary and photoresist chemicals by $10 billion, CMP slurries and pads by $5 billion, and other products by $2 billion. Factors driving these increases include advanced chip packaging, next-generation lithography techniques, growing demand for ultra-pure materials, and innovations that enhance process precision, yield, and efficiency.
Competitive Environment Within the Electronic Chemicals and Materials Market
The market is shaped by prominent global specialty chemical producers and advanced semiconductor material suppliers. These companies focus on delivering high-purity chemicals, innovative process materials, wafer fabrication solutions, and breakthrough material technologies. Their competitive edge stems from product purity, boosting chip performance, ensuring supply chain stability, and aligning closely with advanced manufacturing processes. Being aware of this competitive landscape is crucial for identifying potential partnerships, innovation avenues, and growth prospects within the rapidly evolving semiconductor and electronics material arena.
Leading Market Share Holders in the Electronic Chemicals and Materials Industry
According to The Business Research Company, Merck Group led global sales in 2025 with a 0.5% market share. The company’s electronics division actively serves the electronic chemicals and materials market by providing semiconductor materials, specialty chemicals, photoresists, and process chemicals crucial for chip fabrication and electronic component production, as well as high-performance technology applications.
Market Concentration and Competitive Dynamics
The electronic chemicals and materials market remains fragmented, with the top 10 companies accounting for just 3% of total revenue in 2025. This fragmentation reflects the high technology barriers, strict regulatory standards, demand for ultra-pure materials, complex manufacturing processes, continuous innovation, and the need for consistent quality in semiconductor fabrication. Leading firms maintain their foothold through extensive product portfolios, partnerships with chipmakers, global distribution networks, and ongoing research and development in high-purity chemicals and advanced materials. As demand for next-generation chips and components rises, collaboration, innovation, and geographic expansion will reinforce their market positions.
Top Companies by Market Revenue Share in 2025
The key players by their share of the 2025 market include Merck Group (0.5%), Entegris Inc. (0.4%), Linde plc (0.4%), Air Liquide S.A. (0.4%), Air Products and Chemicals, Inc. (0.4%), BASF SE (0.3%), Tokyo Ohka Kogyo Co., Ltd. (0.3%), FUJIFILM Electronic Materials Co., Ltd. (0.3%), Sumitomo Chemical Co., Ltd. (0.2%), and Resonac Holdings Corporation (0.1%).
Major Companies Driving Innovation and Supply
The electronic chemicals and materials sector features a diverse mix of influential companies including Merck Group, Entegris Inc., Linde plc, Air Liquide S.A., Air Products and Chemicals, Inc., BASF SE, Tokyo Ohka Kogyo Co., Ltd., FUJIFILM Electronic Materials Co., Ltd., Sumitomo Chemical Co., Ltd., Resonac Holdings Corporation, LG Chem Ltd., Global Wafers Co., Ltd., Hitachi High-Tech Corporation, Wacker Chemie AG, Nitto Denko Corporation, UBE Corporation, Sumitomo Bakelite Co., Ltd., Indium Corporation, Materion Corporation, and Wafer World, Inc.
Innovations Shaping the Future of Electronic Chemicals and Materials
One significant area of innovation is the development of electronic-grade solvents that improve chip manufacturing precision, enhance contamination control, and enable production of advanced microelectronics. For example, in August 2024, Eastman Chemical Company introduced EastaPure isopropyl alcohol (IPA), a high-purity solvent designed specifically for semiconductor fabrication. Its fast-drying properties, efficient impurity removal, and compatibility with polar resins improve wafer cleaning and support reliable semiconductor manufacturing.
Corporate Strategies Focused on Growth and Sustainability
Companies in this market are prioritizing the advancement of electronic chemicals and materials to enhance semiconductor performance and manufacturing efficiency. They are also investing in novel chemical formulations to improve product reliability and yield, expanding production capacity to meet rising demand, and adopting sustainable manufacturing practices to ensure regulatory compliance and resource conservation.
Overview of the Electronic Chemicals and Materials Supply Chain and Customer Base
The supply chain involves a broad range of raw material providers such as BASF SE, Merck KGaA, DuPont de Nemours, Inc., Entegris, Inc., Linde plc, Air Liquide S.A., Solvay S.A., Dow Inc., Shin-Etsu Chemical Co., Ltd., Mitsubishi Chemical Group Corporation, Sumitomo Chemical Co., Ltd., JSR Corporation, Tokyo Ohka Kogyo Co., Ltd., Fujifilm Holdings Corporation, Resonac Holdings Corporation, Kanto Chemical Co., Inc., Stella Chemifa Corporation, Avantor, Inc., Cabot Corporation, Versum Materials, Inc., The Chemours Company, Wacker Chemie AG, LG Chem Ltd., ADEKA Corporation, and Dongjin Semichem Co., Ltd.
Wholesalers and distributors include Arrow Electronics, Inc., Avnet, Inc., Digi-Key Electronics, Mouser Electronics, Inc., TTI, Inc., RS Group plc, Newark Electronics, Allied Electronics & Automation, Macnica, Inc., WPG Holdings Limited, Rutronik Elektronische Bauelemente GmbH, Farnell Global, element14, Richardson Electronics, Ltd., Fusion Worldwide, Inc., Smith & Associates, Master Electronics, Inc., Heilind Electronics, Inc., Sager Electronics, Inc., PEI-Genesis, Inc., Powell Electronics, Inc., EET Group A/S, TTI Europe, Inc., and Richardson RFPD.
End users encompass major semiconductor manufacturers such as Taiwan Semiconductor Manufacturing Company Limited, Samsung Electronics Co., Ltd., Intel Corporation, SK Hynix Inc., Micron Technology, Inc., Texas Instruments Incorporated, Qualcomm Incorporated, Broadcom Inc., NVIDIA Corporation, Advanced Micro Devices, Inc., GlobalFoundries Inc., United Microelectronics Corporation, Semiconductor Manufacturing International Corporation, Kioxia Corporation, Infineon Technologies AG, NXP Semiconductors N.V., STMicroelectronics N.V., Renesas Electronics Corporation, Sony Semiconductor Solutions Corporation, ASE Technology Holding Co., Ltd., Amkor Technology, Inc., Powerchip Semiconductor Manufacturing Corporation, Tower Semiconductor Ltd., Vanguard International Semiconductor Corporation, and Bosch Semiconductor Manufacturing.
In summary, the electronic chemicals and materials market is on a strong upward trajectory thanks to expanding semiconductor production, technological innovations, and increasing investments worldwide. The combination of diversified product segments, regional growth dynamics, and strategic corporate initiatives positions this market for continued prominence within the broader chemicals industry through 2030 and beyond.
Our latest 2026 market reports provide expanded strategic and visual intelligence with market attractiveness scoring and analysis, total addressable market (TAM) analysis, company scoring matrix graphics and tables, Excel-based forecasting dashboards, market hotspots infographics, key technologies and future trend analysis, together with updated graphics and tables.
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company
Oliver Guirdham
The Business Research Company
+44 7882 955267
info@tbrc.info
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery